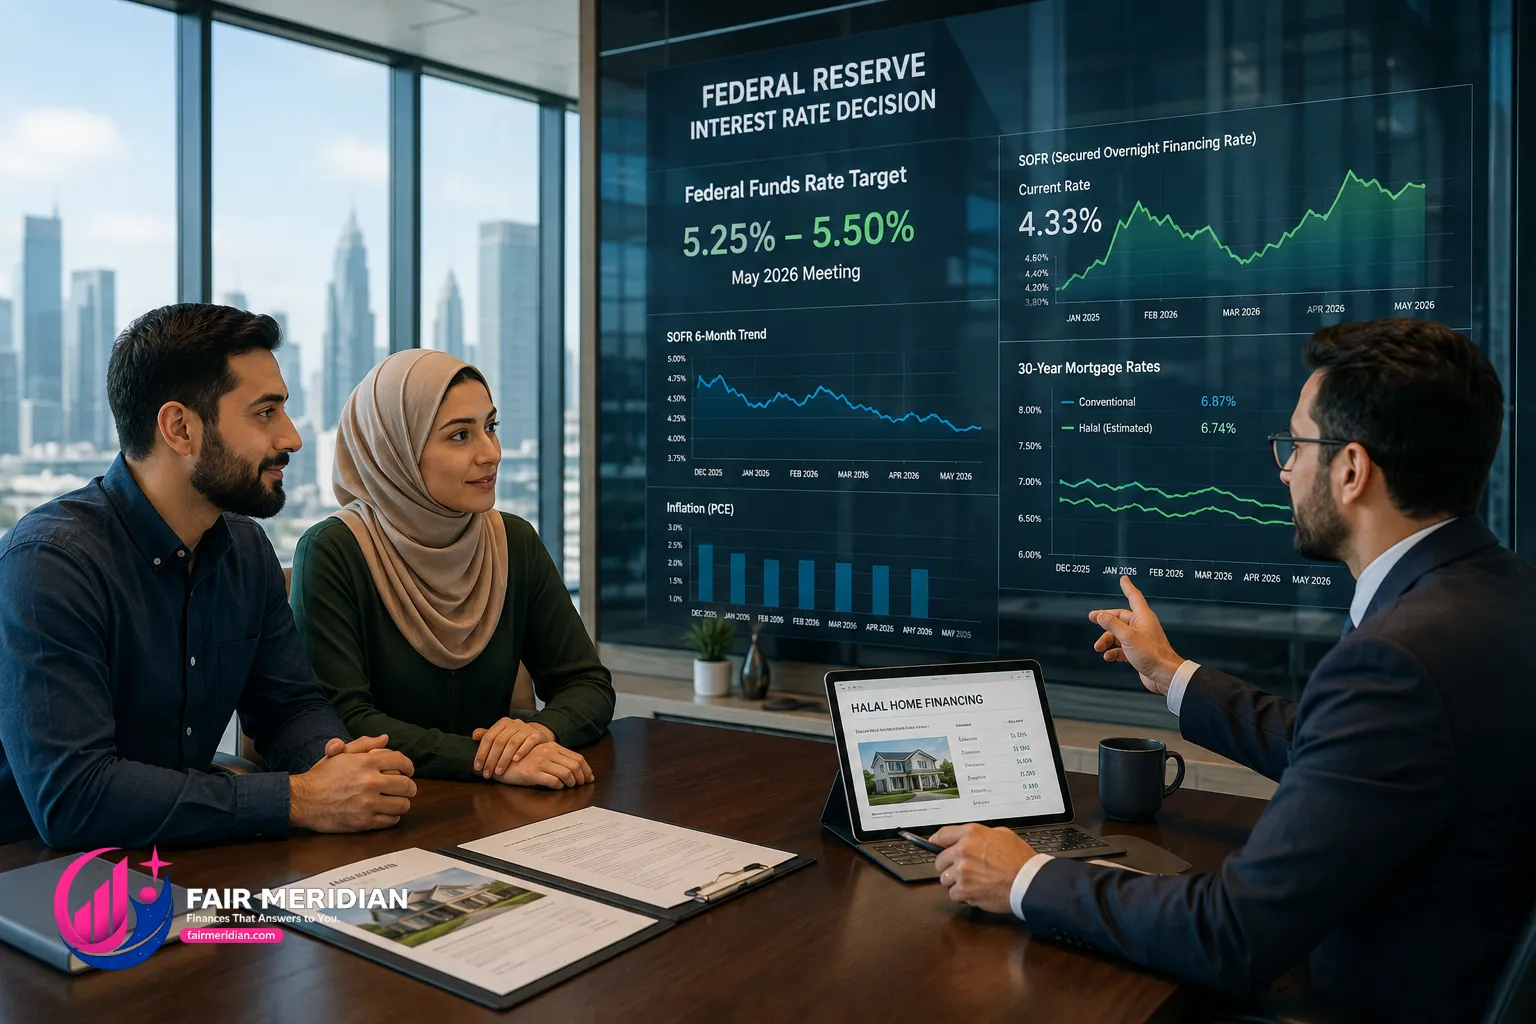
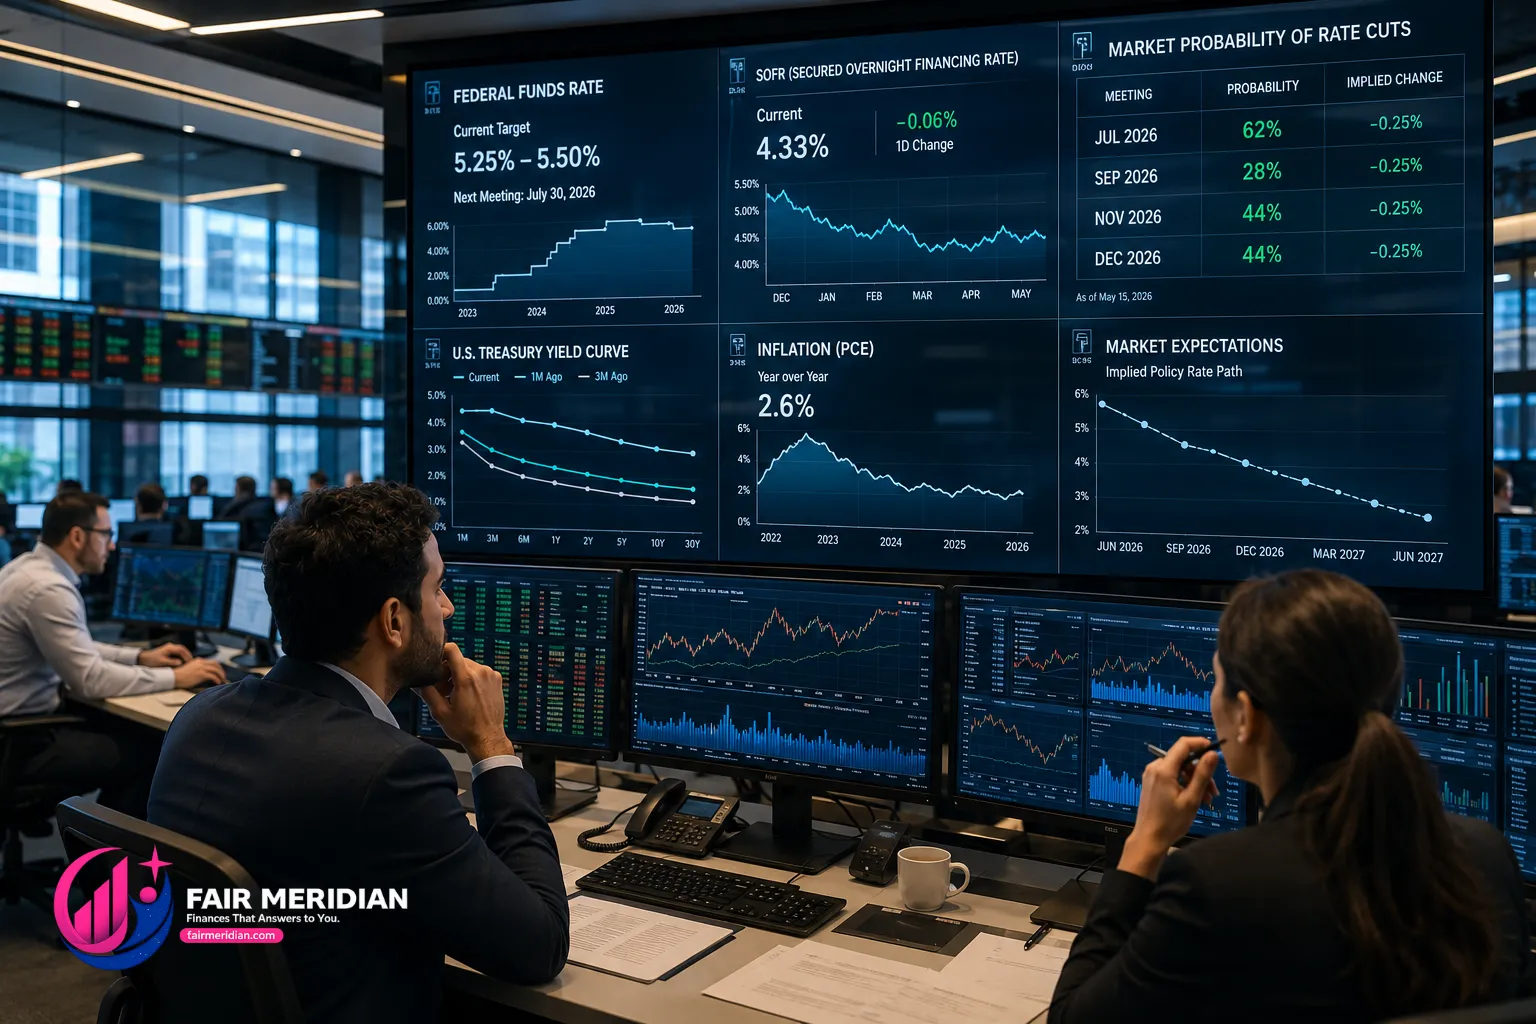
The Federal Reserve held its federal funds rate target at 5.25%–5.50% at its May 2026 meeting, citing continued progress on inflation but insufficient confidence to cut again. Markets immediately repriced their expectations: one cut in July 2026 now carries roughly 62% probability per federal funds futures; a second cut in November or December carries about 44% probability.
If you are a Muslim homebuyer watching halal mortgage rates, here is what the Fed's decision actually means — and what it does not mean.
How the Fed Affects Your Halal Mortgage Rate
The relationship between Federal Reserve policy and your Guidance Residential profit rate involves two steps that most people conflate into one. Understanding both steps tells you why halal rates sometimes move before the Fed acts, why they sometimes don't move even after the Fed cuts, and what to watch to anticipate your next rate quote.
Step 1: Fed Policy → SOFR
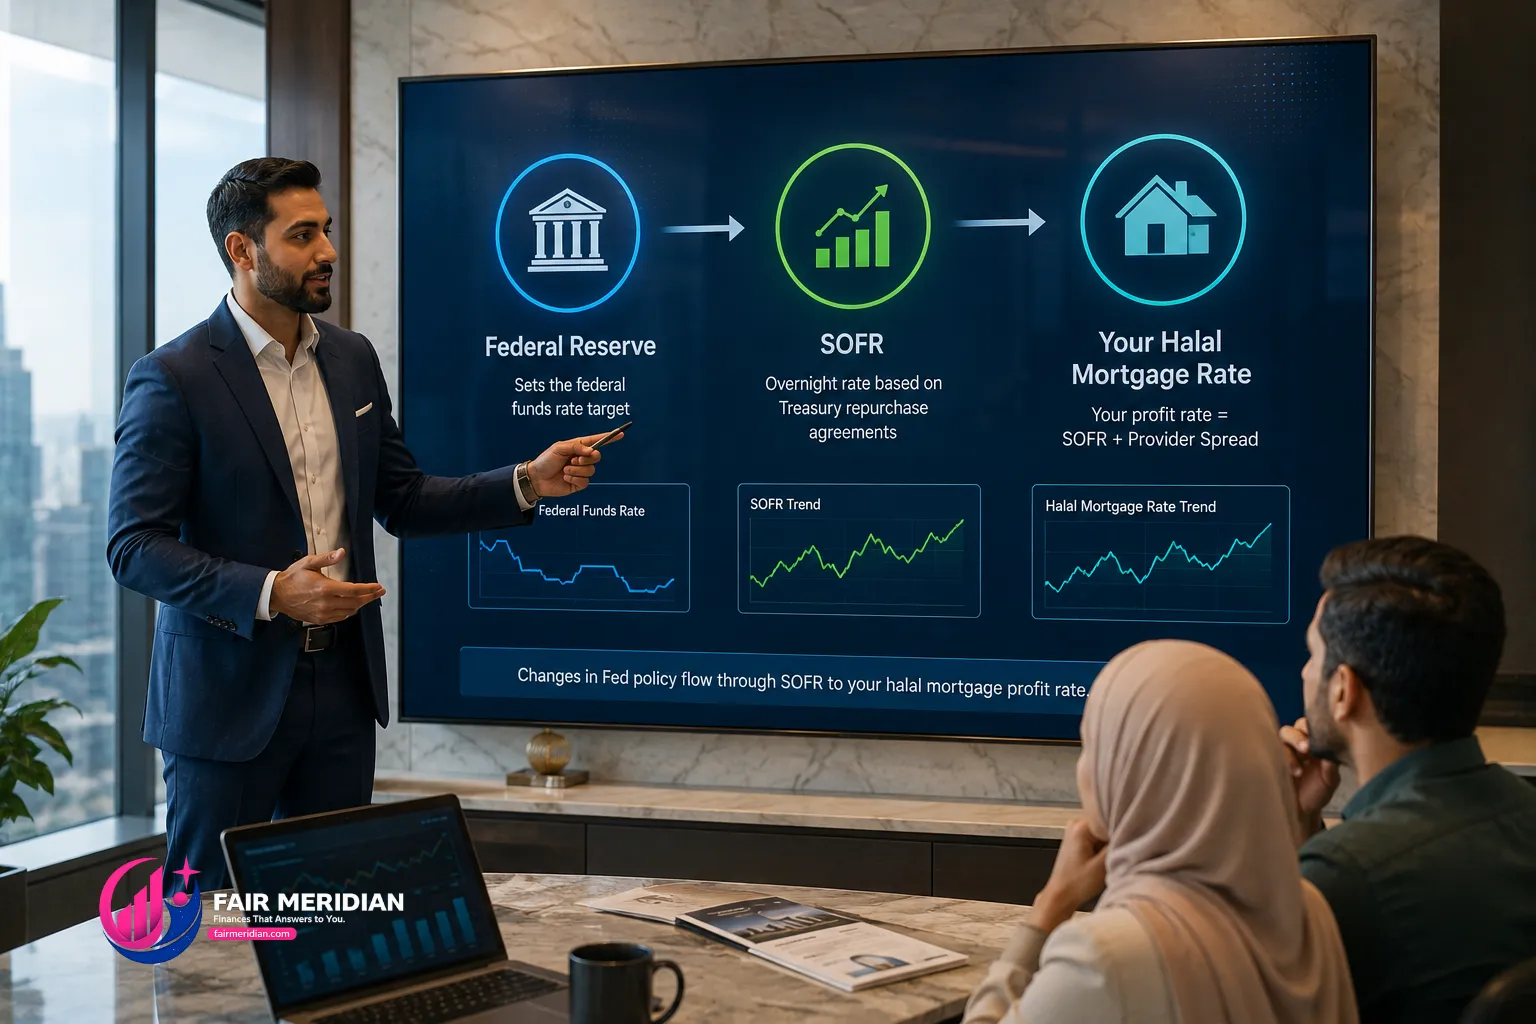
The Federal Reserve sets the federal funds rate — the overnight rate at which banks lend to each other. This rate directly influences SOFR (Secured Overnight Financing Rate), which is the actual benchmark rate used to price US halal mortgage profit rates.
SOFR is published daily by the New York Federal Reserve and reflects the actual cost of overnight borrowing collateralized by US Treasury securities. SOFR tracks the federal funds rate closely but is not identical to it. When the Fed cuts the federal funds rate by 25 basis points, SOFR typically moves by a similar amount within a day or two.
Step 2: SOFR → Your Halal Profit Rate
Every US halal mortgage provider prices their profit rate as SOFR + a spread. The spread covers the provider's cost of capital, operational expenses, and target return. Here is approximately how this works for the current market:
Component | Current Value (May 2026) | Who Controls It |
|---|---|---|
SOFR Base Rate | ~4.33% | Federal Reserve / market |
Provider Spread (Guidance) | ~2.41% | Guidance Residential |
Risk Adjustment (720+ FICO) | ~0.00% (best tier) | Your credit profile |
Guidance Best Rate | 6.74% | Sum of above |
When the Fed cuts the federal funds rate by 25 basis points, SOFR falls by approximately 25 basis points, and Guidance's best rate moves from ~6.74% to ~6.49% — all else equal. A 50-basis-point cut would take Guidance's rate to ~6.24%. A full percentage point in cuts (four 25bp cuts) would bring rates to approximately 5.74% — a level not seen since mid-2023.
Why Rates Sometimes Move Before the Fed Cuts
This surprises many buyers: halal mortgage rates can fall even without a Fed cut. Here is why.
SOFR doesn't just respond to what the Fed does — it also responds to what markets expect the Fed to do. When Fed officials signal cuts are coming (through speeches, meeting minutes, or the dot plot), financial markets price those expected cuts into short-term rates immediately. SOFR can fall in anticipation of a cut that hasn't happened yet. This is why Guidance's rate in January 2026 was approximately 6.90% and is 6.74% in May 2026 — not because the Fed cut rates, but because markets increasingly priced in cuts they expect to happen in H2 2026.
Current Halal Mortgage Rates — Post-May 2026 Fed Meeting
Provider | Rate (720+ FICO) | Change Since Jan 2026 | vs Conventional (6.87%) |
|---|---|---|---|
Guidance Residential | 6.74% | ↓ 0.16% | 0.13% below |
Lariba Finance | 6.85% | ↓ 0.13% | 0.02% below |
UIF Corporation | 6.89% | ↓ 0.12% | 0.02% above |
IjaraCDC | 6.95% | ↓ 0.10% | 0.08% above |
Devon Bank | 7.10% | ↓ 0.09% | 0.23% above |
Conventional 30yr (Freddie Mac) | 6.87% | ↓ 0.15% | — |
Rates as of May 15, 2026. Rate movements since January 2026 reflect market pricing of expected Fed cuts, not actual cuts. Individual rates depend on FICO score, down payment, and income documentation.
What the Hold Means vs What Cuts Would Mean
Today (Fed Holds): Rates Stay Near Current Levels
The May 2026 hold means SOFR stays approximately where it is now (~4.33%), and halal mortgage rates hold near current levels. Guidance Residential's best rate remains around 6.74%. No immediate catalyst for rates to move significantly in either direction.
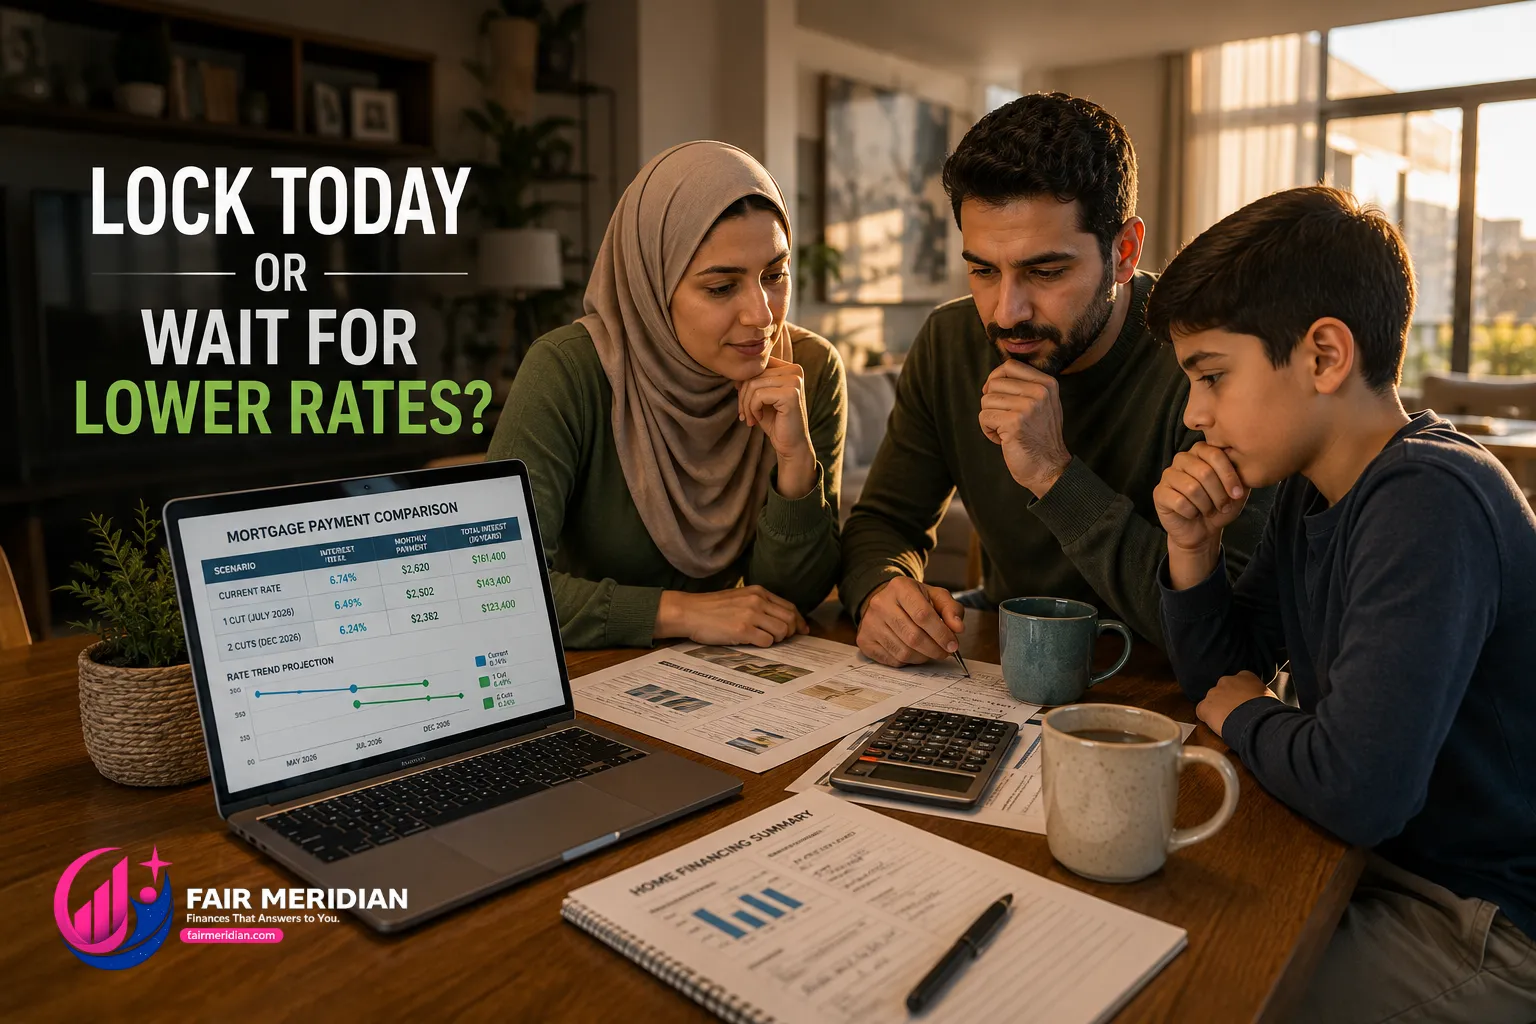
If One 25bp Cut (July 2026 — 62% Market Probability):
SOFR falls to ~4.08%
Guidance best rate: approximately 6.49%
Savings vs today on $400,000 financing over 30 years: approximately $18,000
If Two Cuts by December 2026 (44% Probability):
SOFR falls to ~3.83%
Guidance best rate: approximately 6.24%
Savings vs today on $400,000 financing over 30 years: approximately $38,000
If No More Cuts in 2026 (Rate Reversal Scenario):
SOFR stays flat or rises if inflation re-accelerates
Guidance best rate stays near 6.74% or moves higher
Buyers who waited for lower rates get nothing — current rates represent H2 2026's best
The Lock-or-Wait Decision Framework
This is the question every halal homebuyer is actually asking: should I lock a rate now at 6.74%, or wait to see if July or November cuts bring rates lower?
There is no universally correct answer — but here is the framework to make the right decision for your situation:
Lock Now If...
You have found the right home. Trying to time the rate market while also finding a specific home in a specific neighborhood is trying to optimize two variables simultaneously. If the home is right, the rate is secondary.
The total cost advantage is already significant. At 6.74%, a $400,000 halal financing saves you $161,400 over 30 years vs a conventional mortgage. Waiting for 6.49% saves $18,000 more. Is 6 months of continued renting worth $18,000 in potential savings? For most families, no.
Your rental cost exceeds your projected financing payment. If you are paying $2,800/month in rent and your halal mortgage payment would be $2,600/month, every month you wait costs you $200. Waiting 6 months for a 25-basis-point rate cut costs you $1,200 in rent premium — which would take years of lower rates to recover.
Ask about a float-down provision. Guidance Residential offers float-down options on select programs — if rates fall significantly after you lock, you can take the lower rate at closing. This eliminates much of the lock-or-wait dilemma by giving you rate protection in both directions.
Wait If...
You are still 3–6 months from being ready to buy. If you haven't found a home yet, haven't saved the down payment, or aren't pre-qualified, the rate lock question is premature. Focus on the preparation process. You can lock when you go under contract.
Your credit score needs improvement. A 20-point FICO improvement (from 700 to 720) saves more on your rate than waiting for one Fed cut. Work on your credit first if you are not at 720+.
Your market has seasonal pricing advantages. In some markets, fall and winter home prices are meaningfully lower than spring and summer. If your local market follows this pattern, waiting until October may save more on the purchase price than the rate cut saves on financing cost.
The Halal Mortgage Rate Advantage Is Independent of the Fed
One final point that gets lost in rate-timing discussions: the structural advantage of halal co-ownership financing over conventional mortgages applies at every rate level.
At 6.74% (today): halal buyer saves $161,400 over 30 years vs conventional at 6.87% on a $400,000 home.
At 6.49% (after one cut): halal buyer saves $182,000 over 30 years vs conventional (which also falls, but less, because compound interest benefits more from rate decreases than the declining-balance structure).
At 6.24% (after two cuts): halal buyer saves $199,000.
The structural savings from eliminating compound interest grow as rates fall. Every point of rate decrease helps the halal buyer more than the conventional borrower — because the mathematical benefit of the declining-balance structure compounds more powerfully at lower rates.
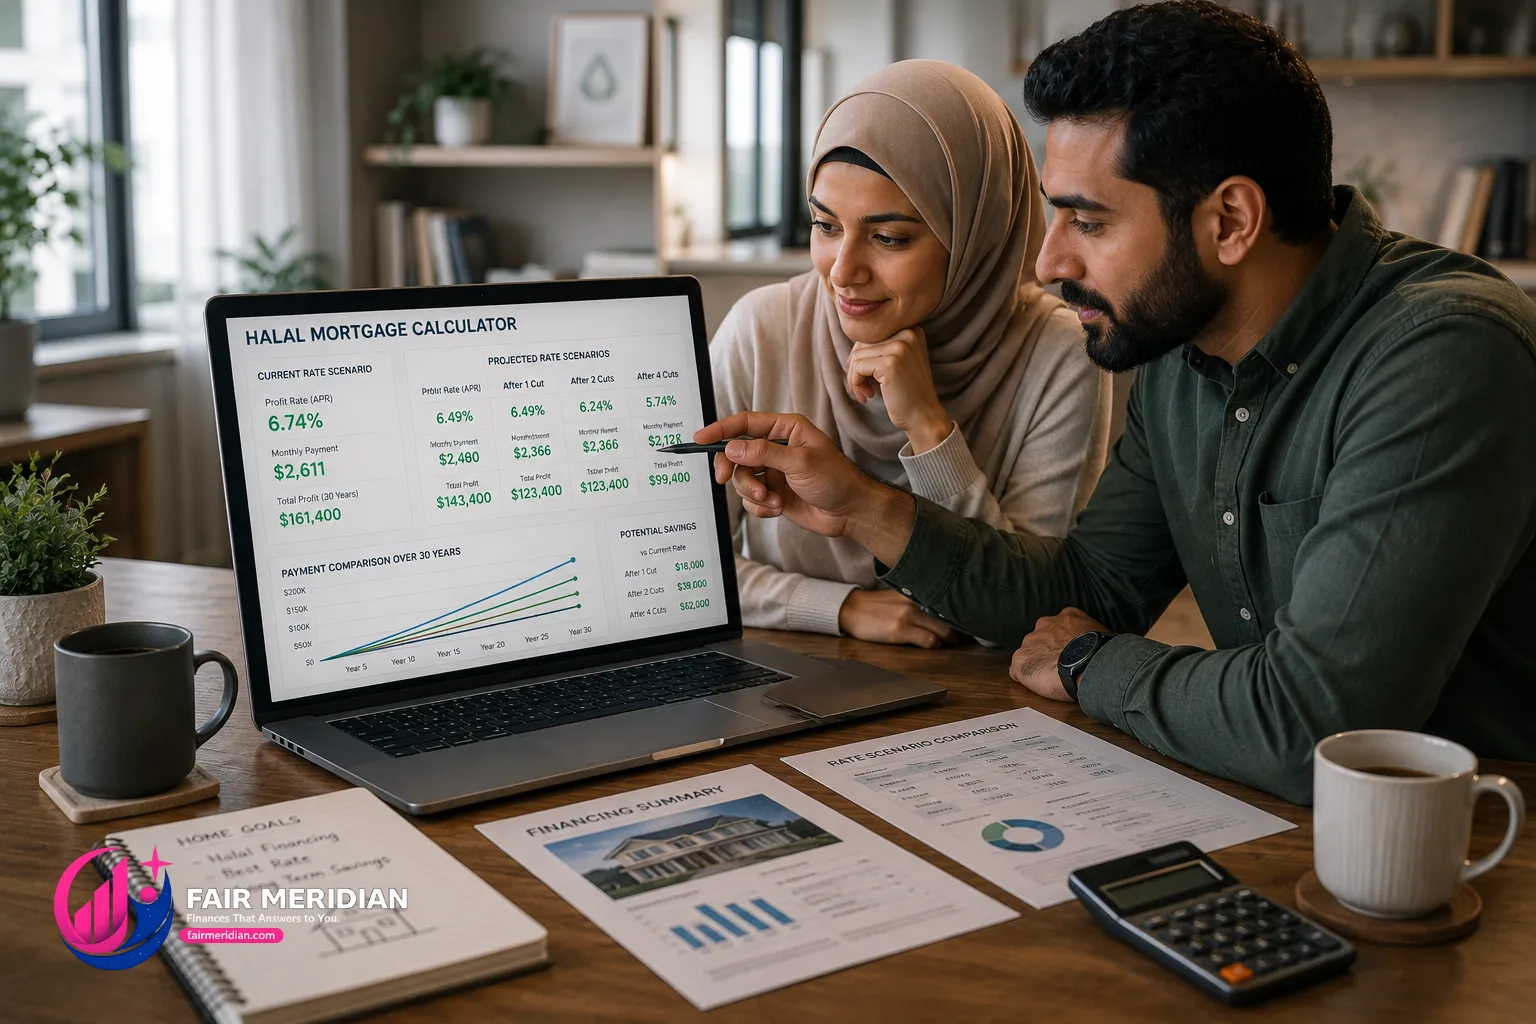
Use our free Halal Mortgage Calculator to model your specific home price at both current rates and projected cut scenarios — so you can see the actual dollar difference that the lock-or-wait decision represents for your situation. For the full current rate table across all five providers, see our Halal Mortgage Rates USA guide, updated monthly.